Blog· November 16, 2026
Property condition assessment report vs. annual satellite condition score
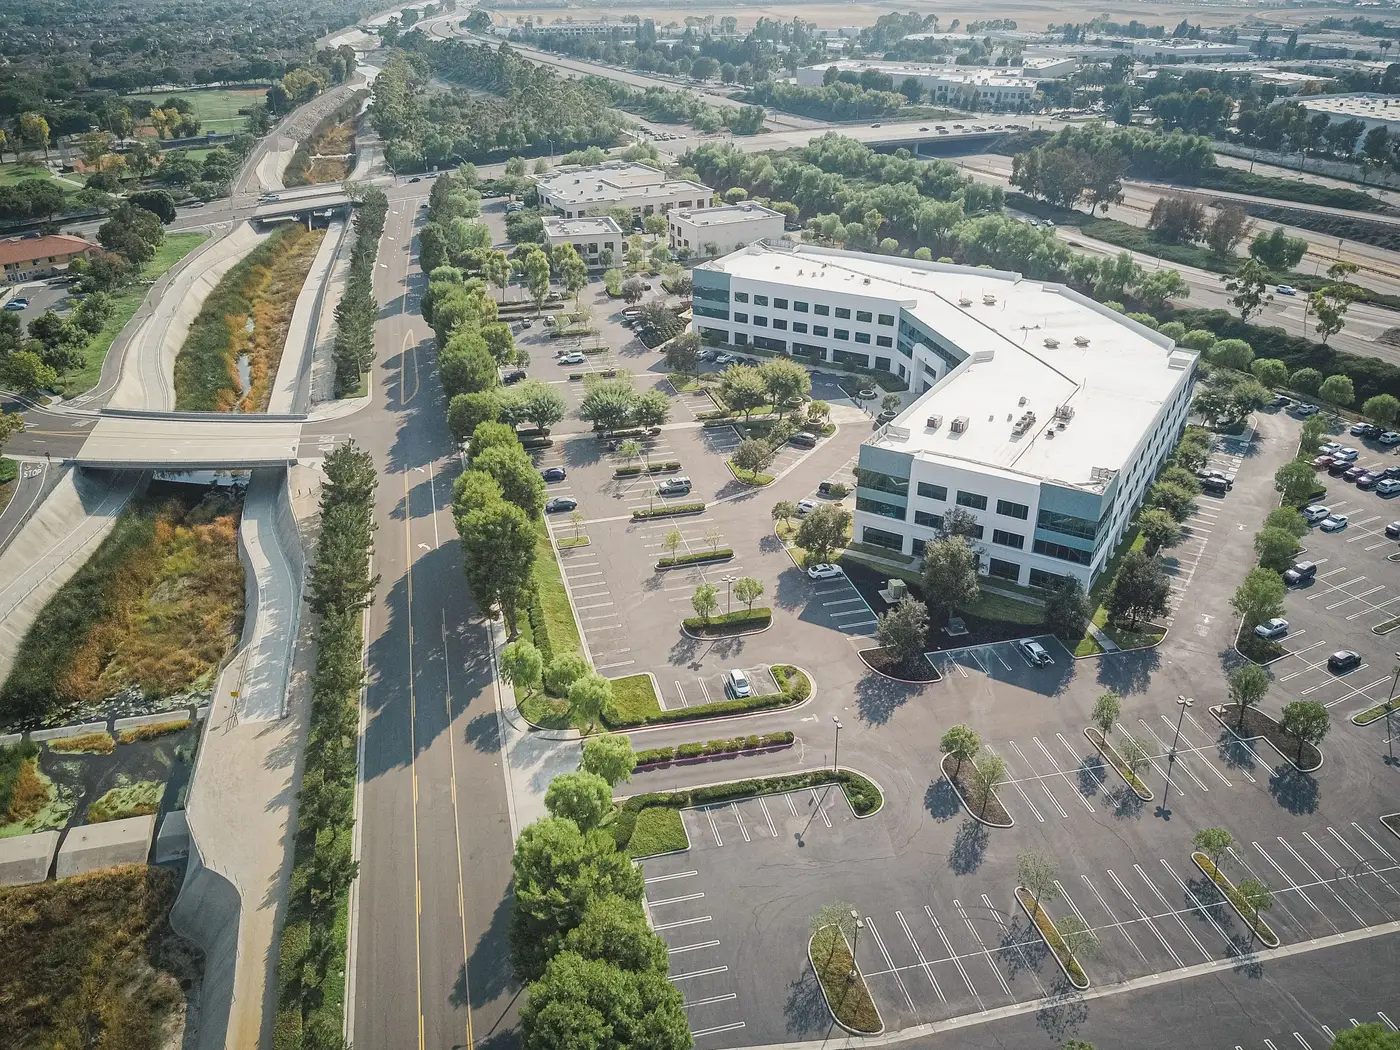
A property condition assessment report and an annual condition score pulled from satellite imagery answer two different questions, and capital planning teams that mix them up end up either over-spending on inspections or under-informed between them.
What a PCA report actually covers
A property condition assessment report is the document your lender, your buyer's counsel, or your insurer asks for at acquisition, refinance, or loan origination. A licensed engineer or a qualified inspection firm walks the site in person, typically following ASTM E2018 guidance, and produces a report covering structural condition, roof membrane and flashing detail, HVAC and mechanical systems, parking lot subbase and striping, and an estimate of remaining useful life for each major component. It ends with a reserve table: dollar figures, by year, for what needs replacing and when.
That report is built for a transaction. It's dated the day the inspector walked the site, it costs real money per address, and nobody commissions one annually across a two-hundred-property portfolio just to see what changed since last year. Lenders require it because they need a defensible, standards-based opinion tied to a specific closing date.
Where the annual condition score fits instead
Between PCAs, most portfolios go years without anyone laying eyes on the roof or the lot at half the addresses. That's the gap an annual satellite condition score is built for. Asset Condition Review runs a very high resolution pass, 0.3 meter GSD or finer, over your full portfolio once a year and scores each site on roof surface wear, parking lot cracking and striping condition, and yard or landscape upkeep. No inspector drives to any address, and no PCA-grade reserve table comes out of it.
Each property gets a numeric condition score across roof, lot, and yard. The full set lands as a ranked list with the worst-scoring properties at the top, plus a GIS layer you load into whatever capital plan tool you already use. It's a flag, not a diagnosis: if the roof score at a property drops sharply between this year's pass and last year's, that's your signal to schedule a closer look, maybe even that formal PCA, before the issue becomes a tenant complaint or an insurance claim. If scores are flat across the portfolio, you've confirmed nothing urgent changed without visiting every site to check.
PCA report vs. annual satellite score, side by side
The PCA report is point-in-time, transaction-triggered, and legally weighted. It's commissioned per property, per deal, and it's what a lender's underwriting file expects to see. The annual satellite score is portfolio-wide, calendar-triggered, and operationally weighted. It's commissioned once a year across every address you hold, and it's what your capex committee uses to decide which properties get budget attention this cycle.
Neither replaces the other. A satellite pass can't open a roof hatch, test a rooftop unit, or certify remaining useful life for a loan file. A PCA can't be run every year across four hundred properties without blowing the capital planning budget before you've spent a dollar on actual repairs. Capital planning due diligence at the portfolio level needs both: the lender-required inspection when a property transacts or refinances, and the annual scan that tells you, for every other property sitting quietly in the portfolio, whether this is the year it needs attention.
Where teams get the sequencing wrong
The mistake we see most often is treating the two as interchangeable, either skipping the annual look because "we already did a PCA three years ago," or commissioning fresh PCAs across the whole portfolio every year because nobody has a cheaper way to check condition in between. The first leaves deferred maintenance to compound unseen. The second burns budget inspecting properties that haven't changed at all.
The sequencing that works: annual satellite pass across the full portfolio to rank condition and catch what's trending down, formal PCA when a property is actually transacting, refinancing, or when the satellite score flags something worth a site visit. One tells you where to look. The other tells you, once you're there, what it will cost to fix.
If your portfolio's last wall-to-wall look was the acquisition PCA and nothing since, an annual scoring pass is a reasonable way to find out what's changed.